Waking up every day with mortgage stress is exhausting. You see the past-due notices pile up, and your stomach drops. It feels like you are completely alone, but thousands of Marylanders face this exact same hurdle every single year.
The most important thing to know right now is that you still have time. A missed payment does not mean the bank will take your keys tomorrow. Maryland has specific legal timelines and protections designed to give homeowners a chance to fix things.
By understanding the rules of foreclosure prevention in Maryland, you can take back control of your situation. Let’s look at the actual, realistic paths available to keep you in your house and stop Foreclosure.
Act Fast When You Miss a Payment
The absolute worst thing you can do is throw the letters from your Servicer into a drawer and pretend they do not exist. Lenders do not actually want your house. Selling foreclosed homes costs them a lot of money and hassle.
Lenders prefer getting paid, even if it means changing the original deal. The earlier you talk to them, the more options they will give you.
- Open every single piece of mail: Look for specific notices about default or intent to foreclose.
- Call your servicer immediately: Use the number on your monthly statement to explain your financial hardship.
- Keep a paper trail: Write down the date, time, and name of every person you talk to.
- Gather your financial documents: Have your pay stubs, tax returns, and monthly bank statements ready.
Understand Your Legal Timeline in Maryland
Maryland law gives you a decent window of time to figure things out, but the clock is ticking. Generally, a lender cannot even file a foreclosure lawsuit until you are at least 120 days late on your mortgage payments.
Before they file anything in court, they must send you a specific legal notice. This warning gives you a clear window to look into official channels for relief.
- Notice of Intent to Foreclose: This must be sent to you at least 45 days before the court case starts.
- Loss Mitigation Application: This form comes with the notice and lets you ask for help.
- The 90-Day Rule: A foreclosure sale generally cannot happen until 90 days after the court case is filed.
Smart Options for Foreclosure Prevention Maryland
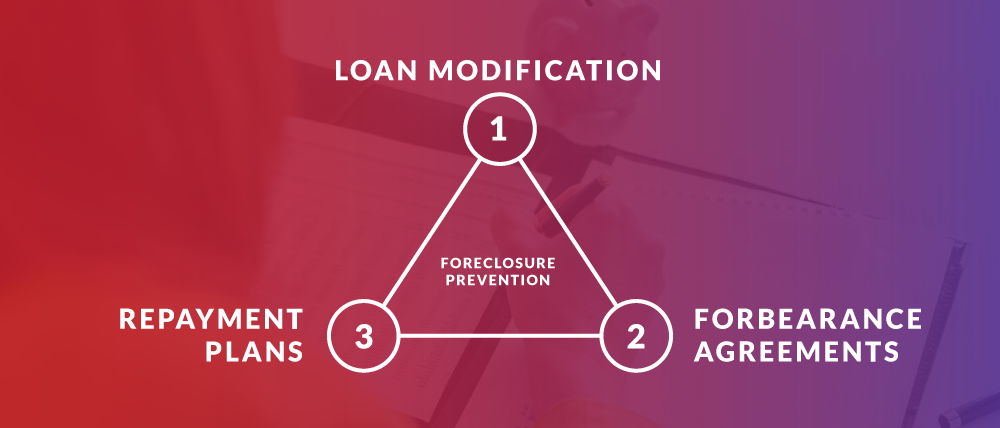
You have several paths to pause or completely stop the legal process. The right choice depends entirely on whether your financial hardship is temporary or long-term.
1. Loan Modification
This is where the lender permanently changes the original terms of your loan. They might lower your interest rate, extend the payoff time to 40 years, or add the missed payments to the back of the loan. This gives you a fresh start with a monthly payment you can actually afford.
2. Forbearance Agreements
If you lost your job but start a new one next month, forbearance is a lifesaver. The bank agrees to pause or lower your payments for a few months. Once the period ends, you agree on a plan to pay back the missed amount over time.
3. Repayment Plans
If your financial hiccup is already over, a repayment plan lets you catch up gradually. You pay your regular monthly mortgage plus a little bit extra each month until your account is fully current again.
Take Advantage of Maryland Housing Mediation
If your lender files a foreclosure action in court, do not give up hope. Maryland has a unique mediation program that brings you and the servicer to the same table.
An administrative law judge acts as a neutral third party to help you negotiate. This is often your absolute best shot at getting the bank to approve a loan modification.
- Request mediation quickly: You only have 25 days to ask for it after the final loss mitigation affidavit is filed.
- Pay the small filing fee: It costs a minor fee to request, but it is worth every penny.
- Show up prepared: Bring updated financial documents to prove you can handle a modified payment.
Watch Out for Foreclosure Rescue Scams
When a foreclosure notice becomes public record, scammers will start targeting you. They scrape court data to find your address and send fake offers.
They make massive promises to save your home instantly if you pay them upfront cash. Real help does not cost thousands of dollars out of pocket.
- Never pay upfront fees: Legitimate housing counselors do not charge you for foreclosure prevention help.
- Do not sign over your deed: Scammers will ask you to transfer the title while they “fix” your loan.
- Never bypass your lender: If a company tells you to stop talking to your bank, run away.
- Avoid verbal promises: Get every single agreement with an entity in writing before celebrating.
How We Can Help You Stay in Your Home
At HomeFree-USA, we know exactly how stressful this season of life is for your family. We have spent over 30 years helping thousands of families avoid losing their homes through direct financial education and foreclosure counseling.
Schedule a consultation today.
Our experienced team works as a bridge between you and your mortgage company. We help you package your paperwork perfectly so the bank takes your request seriously. We have maintained a 0% foreclosure rate among our primary clients because we focus on real, long-term financial stability.
We serve Maryland residents with free, customized guidance to navigate these exact laws. Let us look at your numbers, talk to your lender, and build a concrete plan to protect your home.
Dealing with foreclosure can feel terrifying, but it’s more of a process than a dead end, with a bunch of exit ramps. Loads of people have been in almost the exact same spot you’re in right now and still found a way to protect their homes. So take a deep breath, stop pretending you didn’t see the mail, and bring in a specialist on your side today.
Frequently Asked Questions
What should I do first if I receive a Notice of Intent to Foreclose in Maryland?
You should call a nonprofit housing counseling agency right away, like HomeFree-USA, to look into foreclosure prevention Maryland strategies. Try not to panic, and please don’t ignore the document. Gather your most recent bank statements, pay stubs, and mortgage letters so a seasoned expert can review your paperwork and help contact your lender to submit a formal loss mitigation package before any court action starts.
Can a lender sell my house immediately after I miss one single payment?
No, the lender cannot sell your house right away. Federal rules plus Maryland laws give protections; they set out required timelines. Most times, you have to be at least 120 days delinquent on your mortgage before the lender can even file a foreclosure lawsuit in court. That delay gives you the chance to craft a workable workaround.
What is the difference between a loan modification and a forbearance plan?
A forbearance plan sort of pauses or shrinks your mortgage payments for a short-term squeeze, but later, you have to give that money back. A loan modification, on the other hand, changes the original mortgage terms for real, like reducing the interest rate or adjusting the payment schedule so the new monthly amount is doable, not just temporarily.
Is Maryland housing mediation mandatory for every homeowner who’s facing foreclosure?
No, it is not automatic. You have to ask for it. Once the lender files the final foreclosure papers in court, they must send you a mediation election form. After you receive those papers, you get only 25 days to complete the form, pay the required court fee, and then request the mediation session.